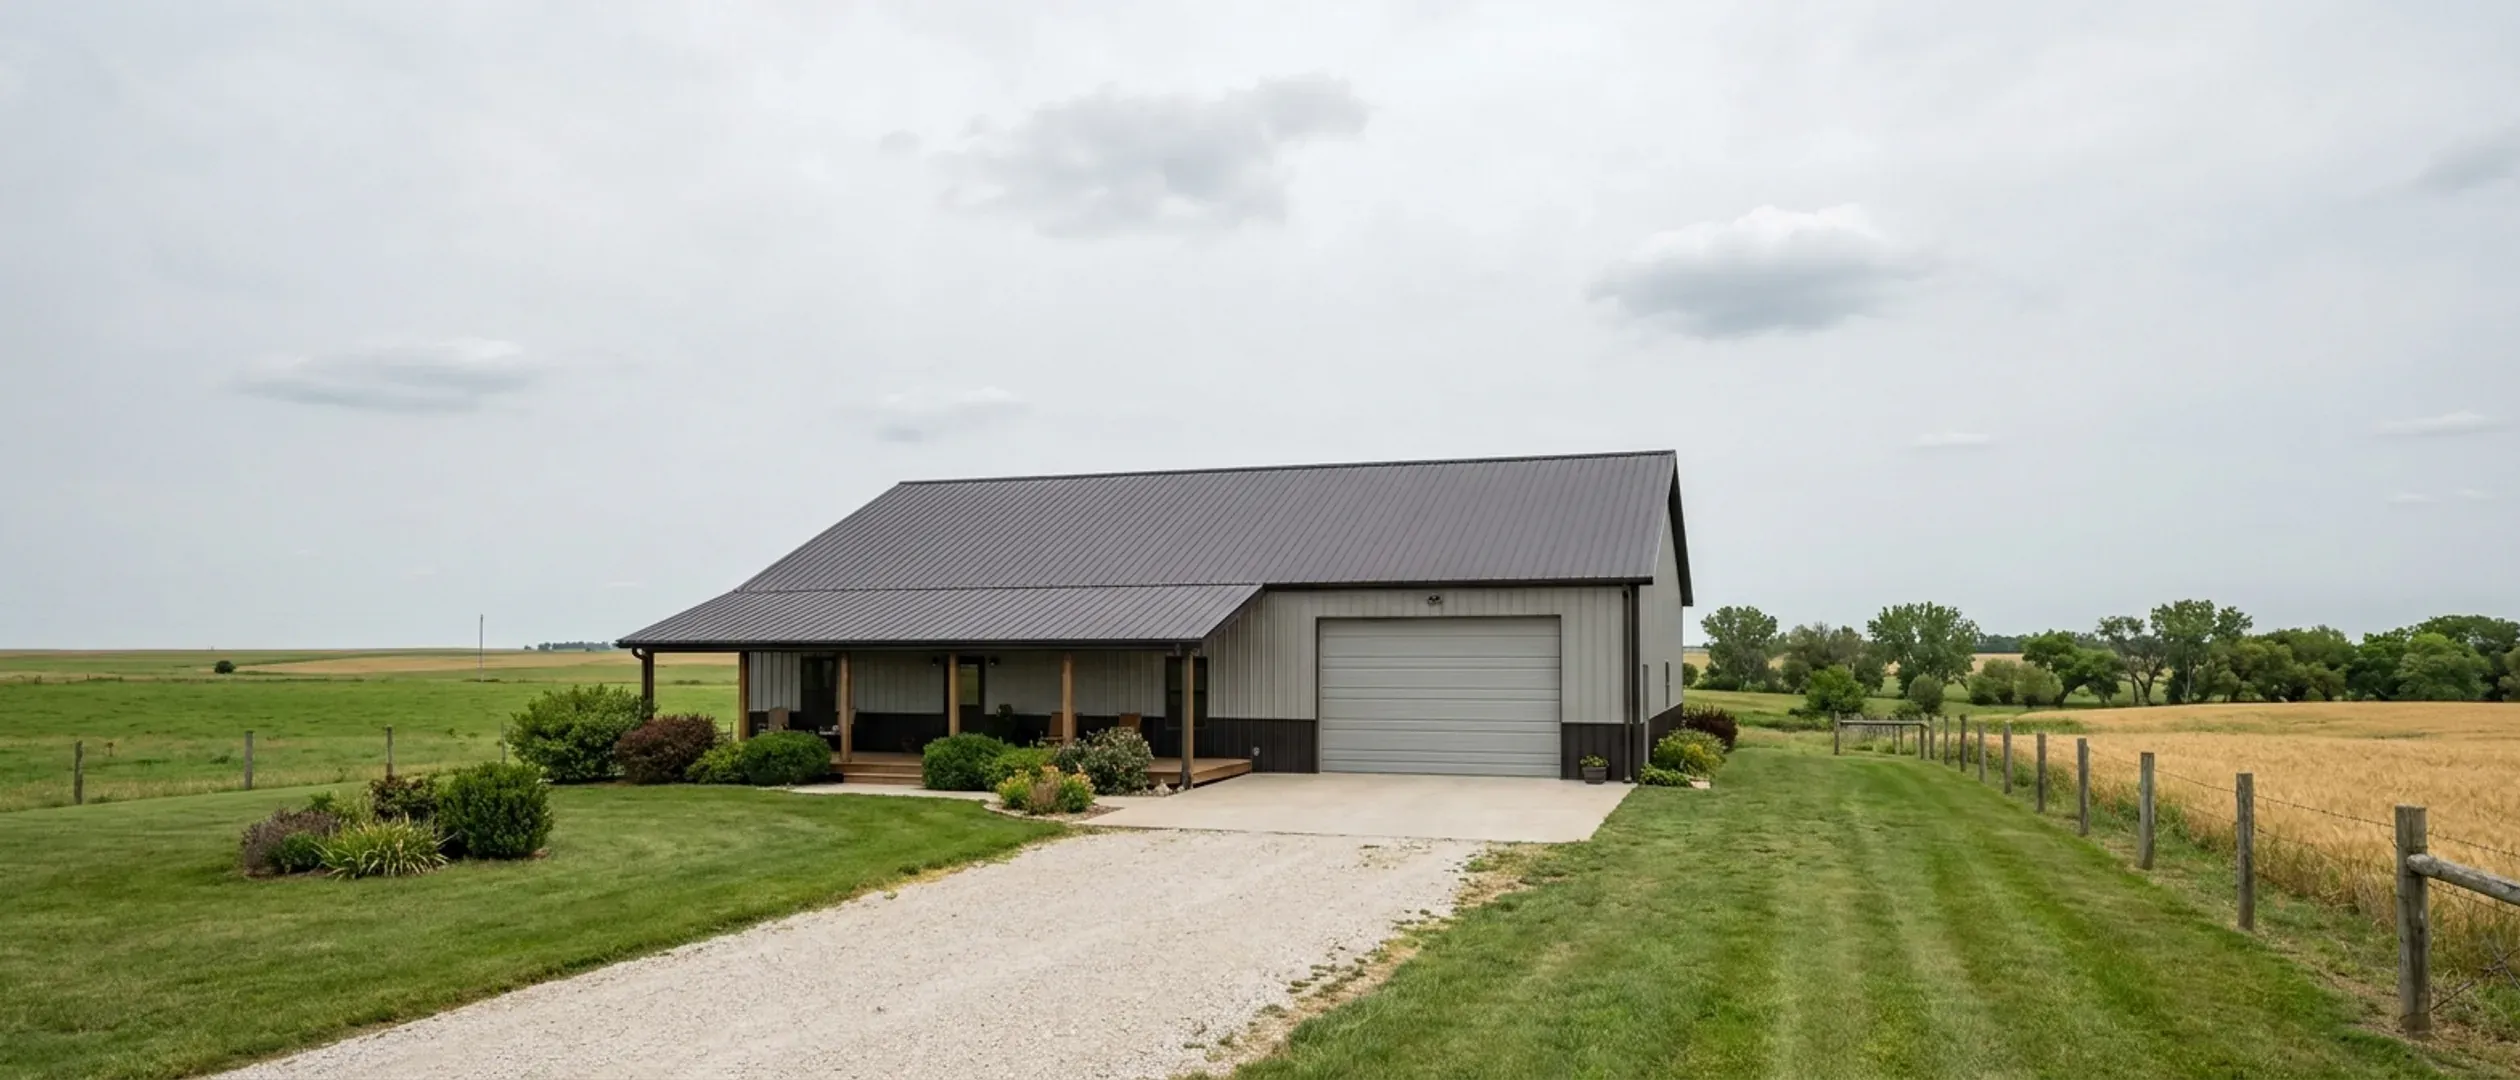
Barndominium Financing in Kansas: Construction Loans, USDA, Farm Credit and KHRC
A barndominium is financed like any custom home built on your own land: a construction loan pays the builder in draws, then converts to a mortgage when the house is finished. What makes it harder is the appraisal. A steel or post-frame house on acreage with a big shop has fewer comparable sales than a subdivision house, and a lender lends against what the appraiser says it is worth, not what it cost. This guide covers who lends on rural Kansas homes, what the federal programs' own rules say about shops and farm ground, and the Kansas program built for exactly the appraisal gap. We are a builder, not a lender. We do not arrange loans, and nothing here is a rate quote or a promise that you qualify.
Figures on this page are cited third-party or government data, not a quote from Kansas Barndominium Builders.
Bottom Line Up Front
- Most custom homes are not paid for with FHA or VA loans. For contractor-built houses started in the Midwest in 2025, the Census Bureau reports 66% financed conventionally, 31% paid in cash, 2% FHA and 1% VA.
- Farm Credit lenders with Kansas offices write construction loans on rural homes: High Plains Farm Credit (Hays) says its Rural 1st program finances barndominium builds, and American AgCredit says barns and shops can be included in the appraised value.
- Kansas Housing Resources Corporation's Home Loan Guarantee for Rural Kansas can guarantee the part of a new-construction loan between 80% and 125% of the appraised value, up to $100,000, in rural Kansas counties.
What actually moves the number
The appraisal, more than the rate
A construction-to-permanent loan is sized against the appraised value of the finished house. If a barndominium appraises below its cost, the gap comes out of your down payment. Ask a lender early how its appraisers value post-frame and steel homes and shop space.
Interest during the build
During construction you normally pay interest only on the amount drawn so far. A build that runs long costs more in interest, so the schedule is part of the financing.
How much land goes in the loan
USDA's guaranteed program requires a site that is typical in size for the area and excludes land used mainly for farming. Farm Credit rural home programs are written for acreage. The more land, the more the lender choice matters.
How much of the building is shop
A lender and an appraiser treat living space and shop space differently, and USDA's rules exclude buildings used mainly to produce income. A plan that is mostly shop with a small apartment is a different loan from a house with an attached garage.
How Midwest custom homes are actually paid for
The Census Bureau's Survey of Construction records how contractor-built homes, the kind built on the owner's own land, are financed.
Conventional loans dominate
For contractor-built houses started in the Midwest in 2025, the Census Bureau reports 66% financed with conventional loans. Nationally the figure was 70%.
Nearly a third pay cash
The same Census table shows 31% of Midwest contractor-built starts paid for in cash in 2025. That usually means land already owned outright plus savings or the sale of a previous home, and it is why so many owner-built projects start from land equity.
FHA and VA are a small share
FHA-insured loans were 2% and VA-guaranteed loans 1% of Midwest contractor-built starts in 2025, according to the Census Bureau. Both programs can finance construction, but few lenders offer them for a one-off custom build, so ask early if you intend to use one.
The construction-to-permanent structure
Most custom-home lenders offer a single loan that funds construction in draws and then becomes the mortgage, with one closing. American AgCredit describes its version as one loan, one set of fees and one closing, from buying the land through building the house. Each draw is released as work is completed and inspected, so a lender's draw schedule shapes your builder's payment terms.
Farm Credit and rural home lenders in Kansas
Farm Credit associations are cooperatively owned lenders that specialise in rural property, and several write home and construction loans on Kansas acreage. Each one's own site describes its program; these are the points relevant to a barndominium.
High Plains Farm Credit
Based in Hays, High Plains Farm Credit says it has six branches and ten outposts across central and western Kansas. Its rural home page lists construction loans and barndominium loans through Rural 1st, and says Rural 1st finances most barndominium builds like traditional construction loans.
Frontier Farm Credit
Frontier Farm Credit, with a mailing address in Manhattan, offers home lending through Rural 1st, including financing to buy land and build a home, lot loans and construction loans.
American AgCredit
American AgCredit lists Kansas offices in Dodge City, Garden City, Great Bend, Hutchinson, Liberal and Pratt, among others. Its rural home loan page says large acreage qualifies, residential and agriculturally zoned properties are eligible, and barns, shops and outbuildings can be included in the appraised value.
Your local bank
Community banks in rural Kansas lend on property their loan officers can drive past, and many keep construction loans on their own books rather than selling them. For an unusual house on acreage that can be an advantage, because the bank sets its own appraisal and land rules.
What USDA's and VA's own rules say
The federal programs are defined in regulation and statute. These are the parts that decide whether a barndominium fits.
USDA direct loans can build a house
Under 7 CFR 3550.52, Section 502 direct loan funds may be used to buy or build an eligible dwelling for the borrower's permanent residence. Eligibility is income-limited: 7 CFR 3550.53 requires household income at or below the area's low-income limit at approval. The dwelling must be modest for the area and not designed for income-producing purposes (7 CFR 3550.57).
USDA guaranteed loans can build a house, but not a farm
Under 7 CFR 3555.101, guaranteed loan funds may be used for the construction or purchase of a new dwelling. The site rules in 7 CFR 3555.201 require a site typical in size for the area, with no income-producing land or buildings used mainly for income, and state that property used primarily for agriculture, farming or commercial enterprise is ineligible.
What that means for a shouse
A shop you use for your own vehicles and projects is a different thing, in USDA's rules, from a shop that runs a business. If the building is mainly a commercial shop, or the parcel is mainly a working farm, the guaranteed program's site rules exclude it. The site must also have direct access from an all-weather road and adequate water and wastewater systems.
VA loans can build a house
38 U.S.C. 3710 lists, among the purposes of a guaranteed VA loan, the purchase or construction of a dwelling to be owned and occupied by the veteran as a home. Finding a lender that offers a VA construction loan is the practical hurdle, which is consistent with the 1% share the Census Bureau reports.
Rates, and what to bring to a lender
No rate on this page is a quote. Construction loans usually price above a standard purchase mortgage, and every lender sets its own.
Where mortgage rates were when this was written
Freddie Mac's Primary Mortgage Market Survey put the average 30-year fixed rate at 7.03% for the week of 24 Sep 2026, up from 6.30% a year earlier. That is a national average for purchase mortgages, not a construction-loan rate.
Plans and a specification
An appraiser values a house that does not exist yet from its drawings and a written specification: square footage of living space and shop, finishes, insulation, mechanical systems. The more complete the package, the less the appraiser has to assume.
A fixed-price contract and draw schedule
Lenders want a builder's contract with a total price and a schedule of draws tied to stages of work. Ask for lien waivers with each draw so subcontractors and suppliers cannot place a lien on your land after they have been paid.
The site answers
Septic approval, a well or rural water commitment, the driveway and power are all conditions a lender may want settled before it funds. Our cost guide lists real Kansas examples of those fees.
Reading this because you are weighing a build? The next step is a plan drawn for your program.
What's different about Kansas
Kansas has a state guarantee aimed at the appraisal gap
Kansas Housing Resources Corporation's Home Loan Guarantee for Rural Kansas (HLG) helps lenders cover the part of a loan for land, building purchase, renovation or new construction in rural Kansas counties that exceeds 80% of the appraised value, up to 125% of it. KHRC caps each guarantee at $100,000. It works through participating lenders, so ask yours whether it takes part.
The First Time Homebuyer program is written for a purchase
KHRC's First Time Homebuyer program offers a 0% loan of 15 or 20% of a home's purchase price toward the down payment and closing costs, forgiven after ten years in the home. KHRC describes it in terms of buying a home, so do not plan a build around it without asking a participating lender.
Farm Credit associations cover Kansas by region
Frontier Farm Credit's mailing address is in Manhattan, High Plains Farm Credit says it has six branches and ten outposts across central and western Kansas, and American AgCredit lists Kansas offices including Dodge City, Garden City, Great Bend, Hutchinson, Liberal and Pratt. Which one serves you depends on where your land is.
Your lender will want the permit answer
Many rural Kansas counties issue no residential building permit, which means no inspection record at the end of the build. Lenders and appraisers usually want some evidence the house was built to a standard, so ask what your lender accepts in a county without inspections before you close. Our Kansas barndominium laws guide covers who regulates what.
Can you get a mortgage on a barndominium in Kansas?
Can I use a USDA loan to build a barndominium?
Can I use a VA loan to build a barndominium?
What if the barndominium appraises for less than it costs?
Does land I already own count toward the down payment?
What interest rate should I expect?
Do you arrange financing?
Can a shop be included in the loan?
Questions answered? Tell us what you want to build and we will put real numbers against it.
Sources
- U.S. Census Bureau — Number of Contractor-Built Houses Started by Type of Financing (Characteristics of New Housing, 2025) — Sheet ContrStartsbyFinancing. Midwest 2025: conventional 66%; FHA 2%; VA 1%; cash 31%. United States: conventional 70%. Read 26 Sep 2026.
- Kansas Housing Resources Corporation — Community Solutions: Home Loan Guarantee for Rural Kansas and First Time Homebuyer — Program text renders in the browser, not in the page source. Read (rendered) 26 Sep 2026.
- Electronic Code of Federal Regulations — 7 CFR 3550.52, Loan purposes (Section 502 direct) — Read 26 Sep 2026 via the eCFR API.
- Electronic Code of Federal Regulations — 7 CFR 3550.53, Eligibility requirements — Income at or below the area's low-income limit at approval. Read 26 Sep 2026.
- Electronic Code of Federal Regulations — 7 CFR 3550.57, Dwelling requirements — Modest dwelling, not designed for income-producing purposes. Read 26 Sep 2026.
- Electronic Code of Federal Regulations — 7 CFR 3555.101, Loan purposes (Single Family Housing Guaranteed) — Construction or purchase of a new dwelling. Read 26 Sep 2026.
- Electronic Code of Federal Regulations — 7 CFR 3555.201, Site requirements — Typical site size; no income-producing land; agricultural property ineligible; all-weather access. Read 26 Sep 2026.
- 38 U.S. Code § 3710 — Purchase or construction of homes (Legal Information Institute) — Read 26 Sep 2026.
- High Plains Farm Credit — Rural Home Loans — Construction and barndominium loans via Rural 1st; land equity toward down payment. Read 26 Sep 2026.
- High Plains Farm Credit — Locations — Six branches and ten outposts across central and western Kansas. Read 26 Sep 2026.
- Frontier Farm Credit — Rural 1st Home Loans — Land purchase and home construction financing via Rural 1st; Manhattan mailing address. Read 26 Sep 2026.
- American AgCredit — Rural Home Loans — One-step construction loan; shops and outbuildings in appraised value. Read 26 Sep 2026.
- American AgCredit — Locations — Kansas offices listed. Read 26 Sep 2026.
- Freddie Mac — Primary Mortgage Market Survey, historical weekly data — 30-year fixed 7.03% week of 24 Sep 2026; 6.30% week of 25 Sep 2025. Read 26 Sep 2026.
Keep reading
The pages that answer the next question this one raises.
Cost to build a barndominium in Kansas
Published construction prices, Kansas land values and real county and water district fees, all sourced.
Read itHow big a barndominium your budget builds
Turning a loan amount into square footage once land and site costs are accounted for.
Read itBarndominium vs. house cost
Which parts of the budget a barndominium shell changes, which is what an appraiser is weighing too.
Read itBarndominium with a shop
The shop-plus-house layout, the one where lender and USDA rules on shop space matter most.
Read itWant a real number instead of a range?
Start the survey and tell us about your land and what you want to build. Include the county and parcel ID if you have them, because in Kansas the jurisdiction, the soil and the well and septic answers change the budget more than the building does. The survey costs nothing.